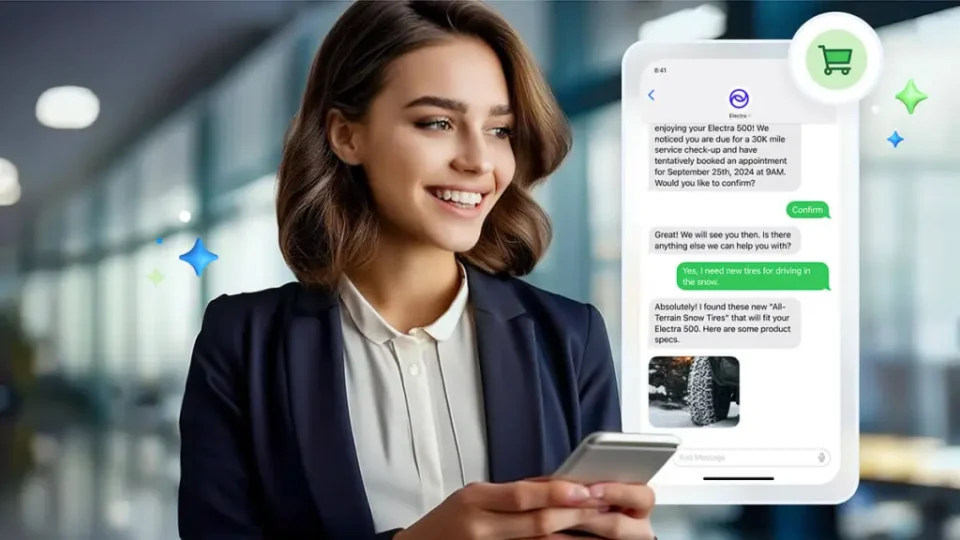
Visa East Africa used Glovo Kenya’s Future of Commerce Summit to spotlight how payment infrastructure must evolve as AI assistants move from recommending products to initiating transactions. Visa cited research showing 89% of respondents would use an AI agent to shop, while only 29% trusted an AI agent to complete checkout.
AI agent payments: shopping assistance versus payment authority
AI shopping assistants can identify products, compare alternatives and narrow choices while leaving the customer to review results and complete checkout. An AI agent that can initiate a transaction plays a broader role: depending on design it may select an item, submit an order or use a payment method according to customer instructions. That raises distinct questions about what instructions the system follows, what limits apply and whether customers will be asked to approve purchases before money changes hands. For example, a customer might authorise an agent to find an item below a specified price without intending to allow additional purchases or unexpected fees; the system must therefore distinguish permission to search from permission to transact.
Tokenisation and transaction-specific tokens
One technical approach discussed by Anne Kinuthia-Otieno at the summit is payment tokenisation, where a substitute value (a token) represents card credentials within a defined payment context. Kinuthia-Otieno spoke about transaction-specific tokens for AI-agent checkout, which can tie payment authority to a particular transaction rather than granting unlimited access to a payment credential. The security benefit depends on implementation: tokenisation reduces exposure of underlying card details but is not, by itself, a guarantee that an AI agent will always make the right purchase or prevent every form of misuse. Tokenisation must sit alongside authorisation controls, transaction limits, clear customer consent and dispute handling.
Controls, accountability and the checkout experience
Trust in AI-led checkout depends as much on control and predictability as on security. Clear approval steps, spending limits, restrictions on authorised purchase types and transaction records that show what happened can help customers understand and control delegated authority. Accountability is also practical: if a customer disputes a purchase initiated by an AI agent, the resolution process must establish what instructions were given, what actions the agent took and how the payment was authorised. For merchants, the checkout must remain clear about final product, price and delivery terms so an agent’s convenience does not obscure purchase terms.
Kinuthia-Otieno also outlined Visa initiatives that support digital payments across channels. Visa Accept was presented as an app-based payment acceptance option for small businesses. Visa Pay was discussed in connection with virtual cards, digital onboarding and cross-border payments. Digitised payment activity can create records of a small business’s sales that may help financial institutions assess trading activity for financing, though such records do not guarantee qualification for credit.
Making AI-assisted commerce practical requires coordination between the AI interface, merchant checkout, payment network and issuing institution, with each part playing a defined role. Tokenisation can help protect payment credentials while transaction limits and clear approval processes define an agent’s scope. Ultimately, whether consumers adopt AI agents for end-to-end purchases will depend on whether the checkout experience preserves clarity and control over what has been authorised.
